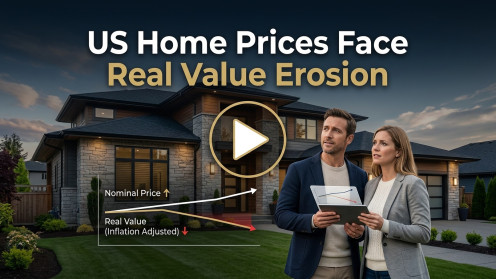
As someone who’s spent more than two decades both brokering and investing in homes, I’ve seen how the numbers tell a deeper story than headlines reveal. In Q2 2026, we watched nominal US home prices continue their upward trend—even as one key federal index essentially held steady from mid- to late-quarter (after accounting for seasonal shifts). Nationally, the annual appreciation rate edged up to about 1.5% by late Q2 (from roughly 1% mid-quarter), but that’s still running about two points behind inflation, now at 3.5%.
What does this mean in real terms? For the 13th month in a row, inflation-adjusted home values actually dipped, though the pace of that erosion has slowed thanks to softer inflation and slightly firmer price gains. It’s worth noting that one federal measure has reported positive yearly appreciation every single quarter since early 2012, which speaks to the underlying resilience of nominal property values—even as real value faces pressure.
As we move into the latter half of the year, affordability remains the number one challenge. Typical monthly payments on existing single-family homes climbed again last quarter, creating real hurdles—especially for first-time buyers. In my own experience, whether I’m guiding a PGA exec through a discreet relocation or advising an investor on a strategic flip, it’s more important than ever to dig into the data, understand the true market dynamics, and craft a plan that protects both value and opportunity.